
Fintech opportunities start where money movement loses continuity
The map points beyond payment interfaces to launch controls, transaction-journey assurance, and recovery when payments or payouts stop.
Introduction
Fintech ideas become credible when they cover the whole operating journey around money. The current evidence adds a sharp reliability layer to the existing controls thesis: customers need clear status, tested transactions, recovery paths, and complete evidence when payment or payout systems fail.
The August 24 Trend Seeker snapshot connects 2,363 ideas to 40,894 distinct signals in this category. That is not a list of businesses to copy. It is evidence about work people fund, problems operators describe, and product gaps founders can investigate.
What the map says now
Fintech combines 16,333 job-ad signals with 12,947 app-review, 6,475 Reddit, 3,530 podcast, 1,234 Product Hunt, and 364 Google Trends signals. The new review layer shows transaction and access failures in real journeys; it does not turn every mobile complaint into a fintech opportunity.
| Measure | Current snapshot | How to read it |
|---|---|---|
| Ideas in this category lens | 2,363 | Ideas can appear in more than one category. |
| Distinct supporting signals | 40,894 | Deduplicated within each source. |
| Fresh signals, 7 days | 1,197 | Recent evidence, not estimated search volume. |
| Fresh signals, 30 days | 7,300 | A check on whether the problem is still active. |
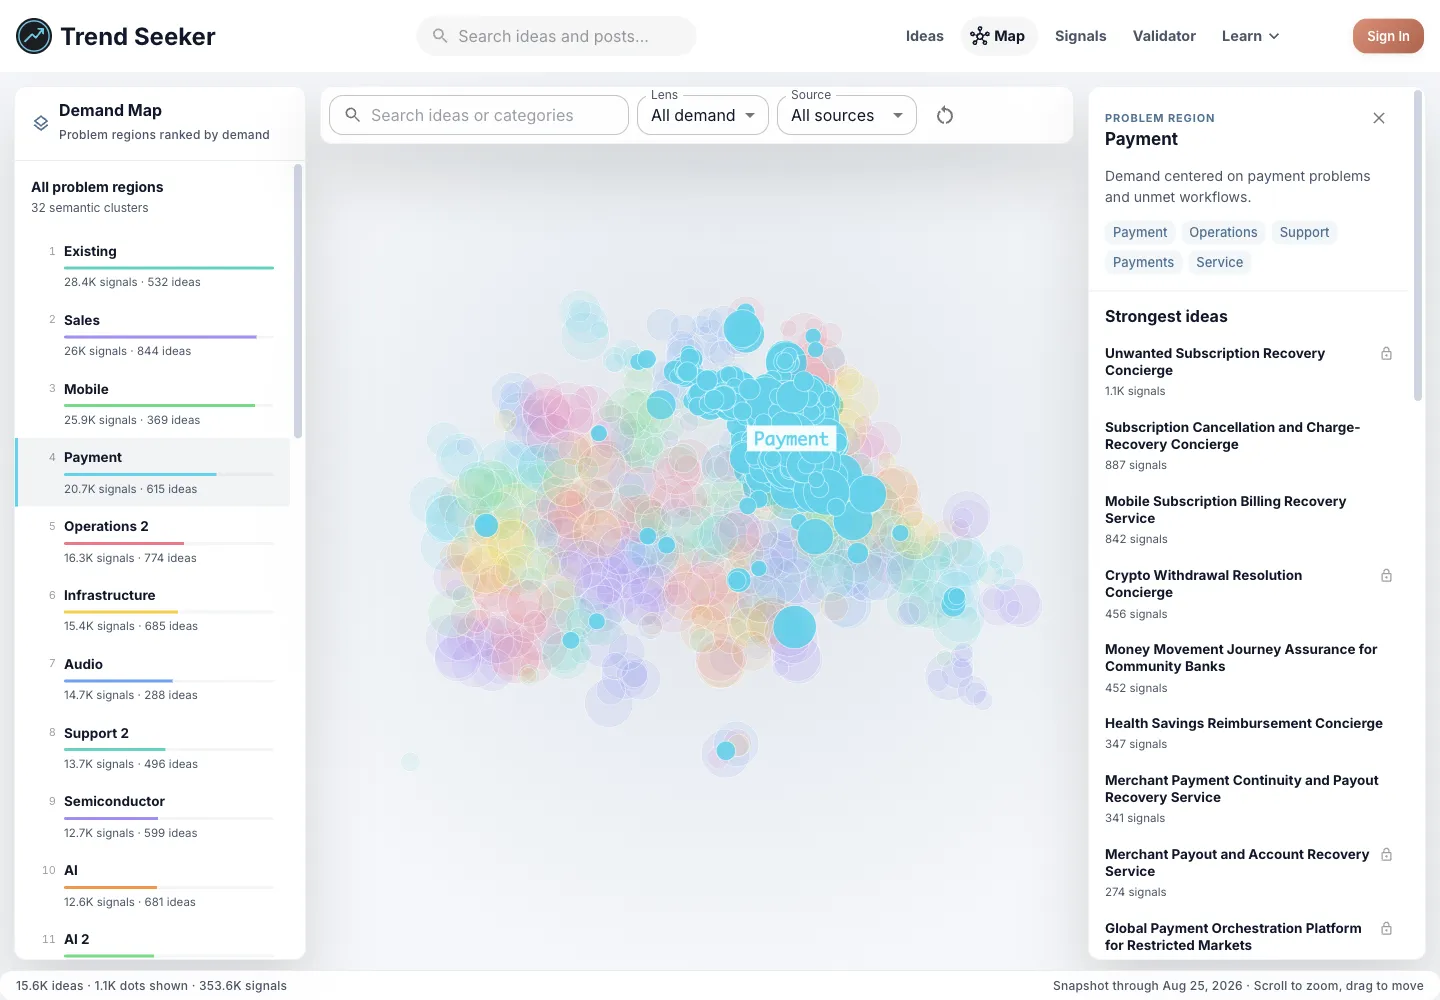
| Payments Gaps | 313 related ideas | The most useful map cluster for this editorial angle. |
The 30-day distinct-signal window changed from 13,262 in the July 21 review to 7,300 now. This compares recent evidence windows, not total market size, search impressions, or purchase intent.
The selected cluster below is one way into the evidence, not the whole category. Open the live Payments Gaps view to inspect the current ideas and signals.
Where the opportunities are
1. Program launches need an operating layer
Card, wallet, lending, and embedded-finance products depend on sponsor, processor, compliance, support, ledger, and reporting workflows. Founders can sell the launch system before building another financial product.
A useful first wedge: Package readiness, partner coordination, control evidence, and first-30-day operating playbooks for one program type.
2. Transaction journeys need assurance
A transfer, deposit, bill payment, or check-cashing flow can fail even when the underlying ledger remains available. Users need accurate status while operators need a reproducible account, device, and transaction trail.
A useful first wedge: Test one money-movement journey across success, delay, retry, duplicate, and support-escalation states.
3. Compliance documentation can become continuous
Scaling teams often reconstruct controls just before an audit. The opportunity is to connect control ownership, evidence, changes, and exceptions to the systems where work already happens.
A useful first wedge: Start with one audit scope and deliver an evidence-ready control register, then automate recurring collection.
4. Continuity is part of merchant payments
Merchants need a plan for processor holds, payout failures, verification requests, and support escalation. The BIS harmonized ISO 20022 requirements show why structured status and consistent payment data matter across participants.
A useful first wedge: Map one merchant's payment dependencies, backup acceptance path, evidence pack, and recovery contacts before an outage.
Three concrete expressions of these patterns are Regulated Product Launch Compliance Office, Money Movement Journey Assurance for Community Banks, Merchant Payment Continuity and Payout Recovery Service. Their cards remain visible below while you read so you can move from the editorial argument to the underlying idea evidence.
Ready to explore fintech business ideas?
Explore fintech opportunities backed by current market evidence.
This FinTech snapshot contains
+2,363ideas
and
+40,894signals


What to sell first
| Opportunity | Sell first | Avoid building first |
|---|---|---|
| Program launch | Launch-readiness package | New consumer wallet |
| Journey assurance | One transaction-state test pack | New banking app |
| Controls | One audit-scope evidence system | Broad GRC replacement |
| Merchant continuity | Processor failure and payout recovery plan | Proprietary settlement network |
Where founders get it wrong
Fintech demand does not remove licensing, sponsor, fraud, capital, data, and customer-protection constraints. A compelling consumer complaint may be expensive or impossible to solve without regulated partners, while an internal control product may face long security reviews.
The map helps discover a problem and find language customers use. It does not prove market size, willingness to switch, purchasing authority, or a durable distribution advantage. Read the job-ad signal guide when the evidence is hiring-heavy, then use the startup validation guide before committing to a build.
A 30-day validation plan
- Choose one costly event. Use a program launch, settlement break, audit request, or new-rail pilot where missed evidence delays money or approval.
- Interview ten people around that event. Include the operator doing the work, the manager accountable for the outcome, and someone involved in purchasing.
- Collect the current artifacts. Ask for the spreadsheet, ticket queue, report, checklist, or handoff that exposes the real workflow.
- Sell a fixed outcome. Define the input, delivery window, acceptance test, and price before automating the work.
- Productize repeated steps. Build software only after several customers need the same decision, evidence, or handoff.
Methodology
This edition uses the Demand Map snapshot generated August 24, 2026, with source data through August 24, 2026. Trend Seeker applied a stable editorial lens using terms such as fintech, payments, banking, lending, insurance, tax, accounting, compliance, treasury, and digital assets. One idea can belong to several categories, so category totals should not be added together. The full classified count is reported even when manual review finds cross-sector noise.
A distinct signal is deduplicated by source and logical signal key. It is not an idea, an idea-signal match, a source record, a Google Search Console impression or click, Google Trends relative interest, or a third-party search-volume estimate. We reviewed the leading ideas and the selected semantic region to form the editorial patterns above. The patterns overlap and should not be summed.
Frequently asked questions
Can I start a fintech business without holding customer money?
Yes. Reconciliation, compliance evidence, implementation, reporting, and operational tools can serve regulated companies without becoming the money-moving entity.
What is a good fintech validation event?
A launch delay, reconciliation break, audit request, manual review queue, or partner handoff with a measurable cost and accountable owner.
How often is this fintech brief updated?
Trend Seeker reviews it every other week; regulatory conclusions still require jurisdiction-specific professional advice.


